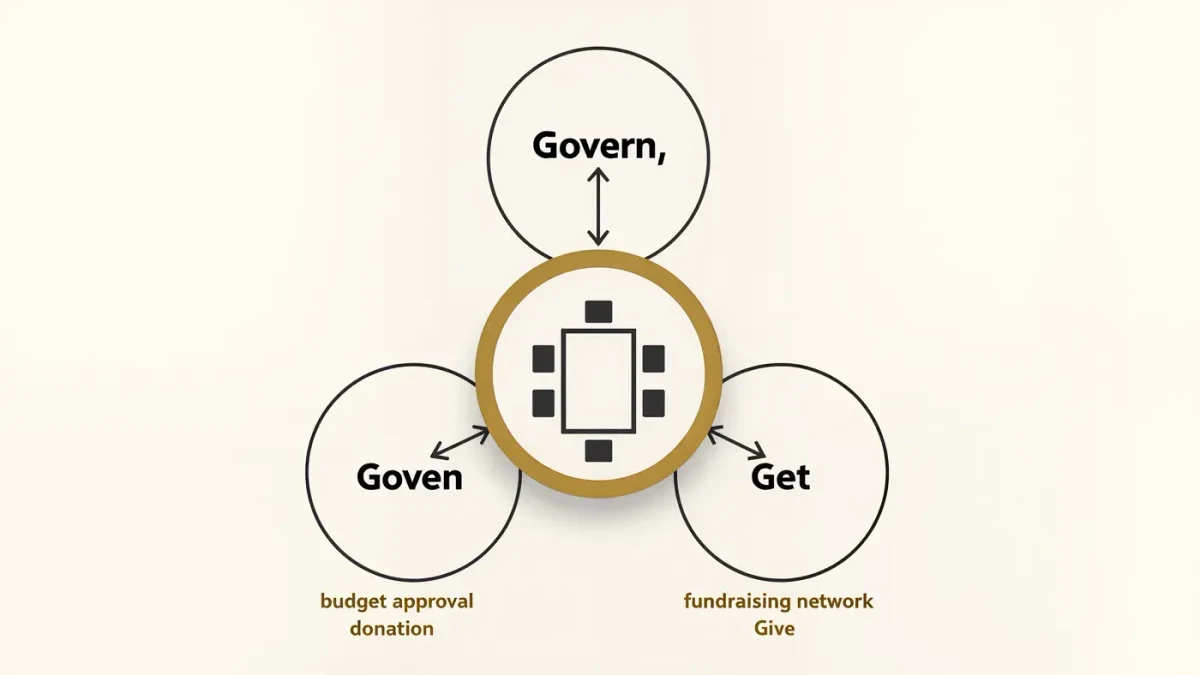
Museum trustees are unpaid board members who legally own fiduciary duty over institutions holding billions of dollars in art, endowment and real estate — and at most American museums, the job comes with an expectation of give/get: personal donations plus funds raised from others, often running to six figures annually per trustee at major institutions. The Met’s board, for reference, is frequently described as one of the wealthiest collections of individuals in the nonprofit world. Trustees raise money, govern budgets, approve directorships — and, uncomfortably often, personally trade in the same art market the museum operates within.
What Do Trustees Actually Do?
Three functions, in descending order of formality. Governance: the board approves budgets, strategic plans, deaccessions, building projects and — decisively — hires and fires the director, usually through a compensation committee whose power makes every director’s tenure a de facto employment at the board’s pleasure. Fundraising: trustees are expected to give personally and to get gifts from networks, which is why development staff compile quiet estimates of each board member’s annual contribution. Access: a trustee’s Rolodex opens donor doors, lends prestige to galas and, at the international level, smooths government relationships.
Board service is unpaid, and the field defends that arrangement as proof of charitable motive. The compensation runs in other currencies: social position, naming opportunities, first looks at exhibitions, and proximity to the market’s best information.
What Is Give/Get?
Give/get is the informal contract at the heart of museum boards: each trustee gives a defined amount and raises more. Practices vary — some institutions set explicit minimums (commonly $50,000 to $250,000+ a year at large museums), others use whispered expectations enforced through committee assignments and, ultimately, non-renewal of terms. Board membership at a major museum is, functionally, a purchased good; nobody says that in the bylaws, everybody says it at the gala.
The result is a selection effect: boards are drawn overwhelmingly from finance, real estate and collecting wealth, which shapes institutional priorities in ways no mission statement advertises — from expansion appetite to which artists get retrospectives.
Where Do Conflicts of Interest Come In?
Everywhere, because most trustees collect art. The entanglements are structural:
- Market information — trustees see what the museum is researching, acquiring or deaccessioning before the market does.
- Valuation effects — a museum retrospective of an artist lifts prices for holders of that artist’s work, and trustees often hold it.
- Dealing through the museum — loans, gifts and purchases can launder market positioning; a partial gift with a cash purchase can let a collector realize value while gaining a deduction.
- Governance over self-interest — trustees at multiple institutions have faced public criticism, protests and even litigation over financing ties (most famously the Sackler family’s naming gifts and the opioid-related backlash that followed).
Formal controls exist — conflict-of-interest policies, disclosure requirements, recusal norms, and in New York a statutory regime requiring fair-market-value review of transactions between museums and insiders under the state’s not-for-profit law after the board-pay scandals of the 1990s (the Bread and Puppet-era reforms of Attorney General Eliot Spitzer and, before him, the 1980s Met-era probes). Enforcement, though, depends mostly on the board policing itself, which is a bit like asking a dinner party to audit the wine list.
How Much Power Do Trustees Have Over Directors?
Near-total, quietly exercised. Directors serve at the board’s pleasure; a president or board chair can end a directorship in a season, and the art world’s history is littered with abrupt departures that were officially “mutual.” The leverage runs through money: since trustees supply the revenue the director cannot generate from admissions alone, dissent is expensive. The most-studied recent case of board power is the removal of Warren Kanders from the Whitney board in 2019, after staff and activist protests over his company’s sale of tear gas — a rare instance of internal revolt defeating a vice chairman, and proof of how exceptional the defeat was.
Boards also steer through softer channels: committee seats, exhibition timing, the acceptance or rejection of directorial hires. A skillful director manages upward as much as outward, and the average tenure statistics of the 2020s suggest the job’s burnout is real.
Who Watches the Watchers?
State attorneys general, theoretically — charitable trusts are their jurisdiction, and New York’s AG has been the field’s most active regulator, from the Whitney-era protest cycle to investigations of deaccessioning. The IRS polices self-dealing at the 501(c)(3) level. The press and staff unions have become the de facto fourth branch: the 2010s–20s produced a sustained wave of journalist and worker scrutiny of trustee money — from Sackler opioid money to donor influence over programming — that no governance manual anticipated.
Frequently Asked Questions
Are museum trustees paid?
No — board service is unpaid, and that is presented as the guarantee of charitable intent. The real compensation is social and informational: status, naming rights, proximity to artists and dealers, and early sight of what the museum is buying, showing or selling.
What does give/get mean?
It is the fundraising expectation that each trustee personally donates and raises funds from others, often against explicit or implied minimums at major institutions. Give/get is the reason museum boards are recruited from wealth rather than expertise — the budget, not the CV, is the qualification.
Can a trustee sell art to their own museum?
Only with disclosure and, under rules like New York’s not-for-profit law, independent fair-market-value review of insider transactions. Museums generally prefer partial gifts or purchases at independent appraisal — but the incentive to realize value through the institution is exactly why the rules exist.
Who has more power, the director or the board?
The board. It hires, evaluates and can dismiss the director at will, controls the budget and approves every major decision. Directors shape culture and programming; trustees decide whether the director keeps doing so.
Have trustees ever been forced off a board?
Rarely, and usually by pressure rather than bylaw. The 2019 departure of Warren Kanders from the Whitney — amid protests over tear-gas sales — is the canonical modern case, notable precisely because staff and activist campaigns so seldom beat a major trustee.